By: Natalie Johnson
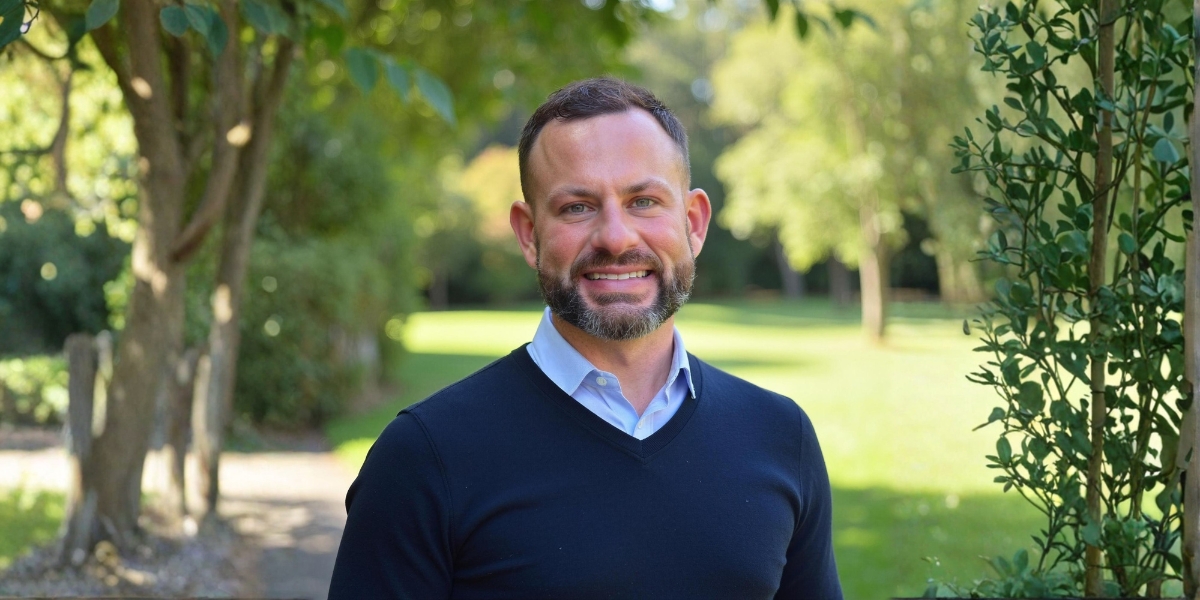
For many business leaders, a commercial property insurance renewal feels like an unavoidable administrative routine rather than a strategic opportunity. Often, the process gets handed over to a broker with the simple hope of securing a workable number. Dave Nickelson-Rueschhoff, National Complex Property Practice Leader at OneDigital, sees this common sequence entirely differently. Having spent years working across both underwriting and broking, he knows that the paperwork initially sent to carriers holds the real leverage over final costs.
Structuring a Strategic Narrative
Approaching market outreach passively remains a common industry pitfall. Professionals frequently pull together basic numbers, attach a generic loss history, and wait for a competitive response. Those habits usually backfire in preventable ways. “Where most brokers fall down is the same place they always have: they show up late, say little, and call it service,” Nickelson-Rueschhoff notes. He suggests shifting the entire paradigm to get better results. Presenting files to the market should act as a proactive pitch instead of a late-stage formality. A strong package outlines management quality, highlights safety improvements, and addresses potential objections before the market can even ask questions. “Treating a submission as a strategy means that it is your first and most important opportunity to influence how underwriters think about, price, and compete for a risk, not just compliance after the fact,” he explains.
The Heavy Cost of Missing Details
When applications arrive missing critical details, underwriters rarely offer the client a free pass. Leaving blanks for a carrier to decipher often translates into direct financial penalties. “Underwriters are not optimistic evaluators. When a submission comes thin, disorganized, or lacking in narrative, they do not give the risk the benefit of the doubt; they fill the gaps conservatively, and conservative assumptions equal higher pricing, broader exclusions, or outright declinations,” Nickelson-Rueschhoff shares. Carriers have to evaluate complex properties from behind a desk and rely explicitly on the provided narrative. If an account shows several recent claims, those incidents might look like a severe operational flaw unless someone explains the corrective actions taken afterward. Without that crucial background context, the insurer has no choice but to build a larger buffer into the quote. “Underwriters price uncertainty, not risk. This is the one brokers miss most,” he warns.
Recognizing the hidden mechanisms of an insurance carrier completely changes how one should prepare a submission. A frequent misconception is that insurers evaluate every individual company solely on its own isolated merits. That assumption ignores the broader corporate goals shaping every final decision. “Underwriters are making portfolio decisions, not account decisions. Most brokers go in thinking the underwriter is evaluating one risk by itself. That is not true,” Nickelson-Rueschhoff points out. An insurer might already carry too much exposure in a specific geography or industry sector. Simply dropping a file onto their desk without verifying their current appetite guarantees wasted effort. Additionally, the underwriter at the carrier level typically needs approval from an underwriting manager or senior leadership to finalize terms. Submitting early gives them the necessary time to secure internal support and advocate for better conditions.
Crafting a Highly Effective Presentation
Standing out in a crowded market requires careful attention to clarity and logical flow. The primary objective should be answering potential concerns clearly so the carrier does not have to hunt through disorganized documents. Handing over clean data allows the underwriter to issue a quote quickly and with high confidence. As Nickelson-Rueschhoff says, “A winning submission is about two things: removing friction and telling a story.” Building this narrative needs to start ideally three to four months before a policy expires. Sending paperwork at the last-minute signals distress and practically forces the incumbent carrier to hold onto the business with maximum leverage. Presenting data early and deliberately displays a deep level of professional sophistication. Cultivating this relationship pays massive dividends when trying to place difficult accounts down the road.
When industry conditions inevitably soften and capacity returns, competing carriers will try to win business by driving rates down. The immediate reflex for most executives is to pocket a modest price drop and move on quickly. Taking that easy road leaves significant value untouched and ignores lingering structural vulnerabilities. “The durable wins in a soft market are not price drops, which reverse fastest when conditions tighten; they are structural improvements, broader terms, increased CAT sublimits, more favorable deductible structures, and coverage restrictions pushed back that were forced on you during the last cycle,” Nickelson-Rueschhoff explains.
Periods of favorable pricing create the perfect window to update property valuations and aggressively document major risk improvements. Utilizing this breathing space effectively ensures a company remains highly attractive when the insurance cycle tightens up again. Rather than blindly chasing the cheapest available premium, smart organizations lock in resilient structural advantages. Summarizing the realities of market cycles, Nickelson-Rueschhoff adds, “The truth is, in soft market cycles, hard markets will eventually come back. The only question is whether you and your clients were ready for it.”
Follow Dave Nickelson-Rueschhoff on LinkedIn for more insights on commercial property insurance, underwriting strategies, and risk management.