Business buyers often discover earnings discrepancies late in due diligence, making early financial verification essential before major acquisition commitments.
A business acquisition can look promising on paper. The seller presents strong annual earnings and an attractive adjusted EBITDA figure. A buyer begins negotiations, signs a letter of intent, and invests time and money in the transaction, only to discover later that some reported earnings cannot be supported by the underlying financial records.
This challenge is particularly relevant in the small and lower middle market, where seller-reported figures can influence acquisition decisions before buyers independently examine the supporting evidence. For a $5 million acquisition, discrepancies can have significant implications for valuation, financing, and the transaction itself.
TrueQoE, a financial analysis platform founded by M&A adviser Mark B. Hirsch, addresses this problem by bringing preliminary earnings analysis earlier into the acquisition process. Its approach centers on a fundamental question: How much of the seller’s earnings story can the available financial documents actually support?
The Gap Between Reported Earnings and Financial Reality
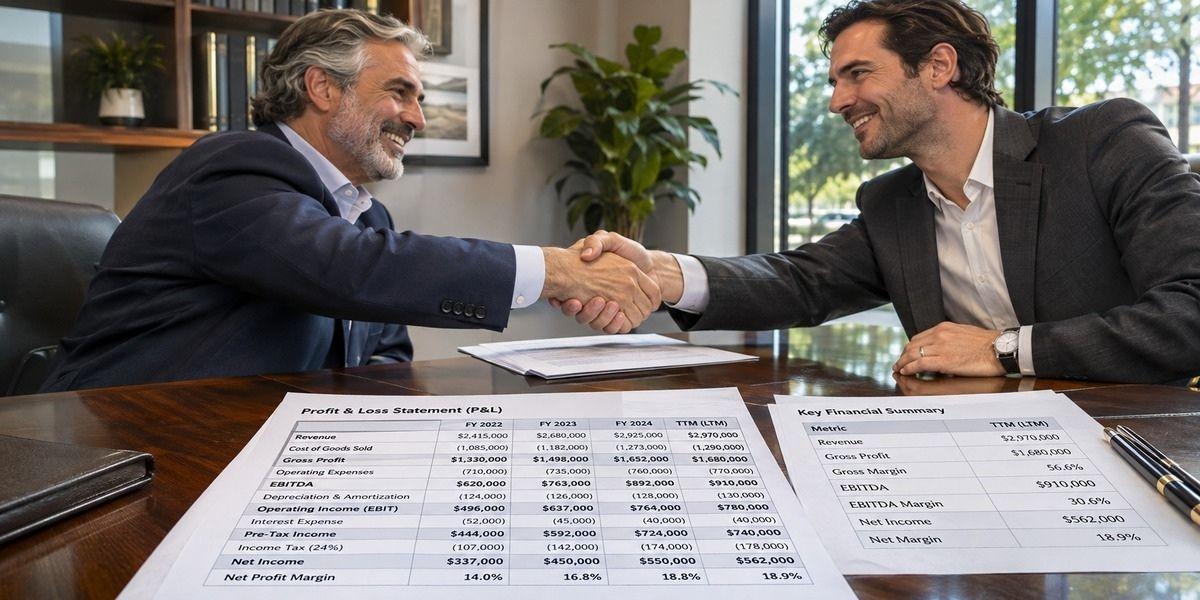
Business acquisitions typically begin with seller-provided financial information, including profit and loss statements, tax returns, balance sheets, and calculations of the seller’s discretionary earnings or adjusted EBITDA. These figures help buyers assess a company’s financial profile, but reported earnings are not necessarily independently verified.
One important consideration is add-backs: expenses sellers identify as nonrecurring, discretionary, or unrelated to ongoing operations. These may include owner compensation adjustments, personal expenses, unusual professional fees, or one-time costs. Some are reasonable and documented; others may be inadequately explained or unsupported.
Accepting these adjustments without sufficient examination can lead buyers to rely on earnings figures that do not accurately reflect the company’s performance. Reported earnings describe what the seller presents; evidence-supported earnings reflect what the available documentation can substantiate.
Why Financial Red Flags Often Surface Too Late
In many transactions, detailed financial scrutiny becomes a priority only after the buyer and seller sign a letter of intent (LOI). By then, buyers may have already engaged attorneys, accountants, lenders, and other advisers while investing considerable time in negotiations and operational reviews.
Financial inconsistencies discovered at this stage can complicate the transaction. Claimed adjustments may lack supporting invoices, revenue figures may not reconcile with tax returns or bank records, and supposedly nonrecurring expenses may be part of normal operations.
Such findings may require buyers to request additional documentation, reconsider financing assumptions, renegotiate the purchase price, or abandon the opportunity. Delays can also increase professional costs and divert attention from other potential acquisitions.
These discrepancies do not necessarily indicate intentional misrepresentation. Records may be incomplete, and buyers and sellers may interpret adjustments differently. The challenge is determining what the available evidence supports before unresolved questions become expensive obstacles.
The $5 Million Acquisition Problem Is About Timing
Consider a hypothetical business marketed with $1 million in adjusted EBITDA and valued at a 5× earnings multiple, implying a $5 million valuation.
If $150,000 in claimed add-backs cannot be supported by the available documentation, excluding those adjustments produces an adjusted EBITDA figure of $850,000. Applying the same 5× multiple results in an illustrative valuation of $4.25 million, a $750,000 difference from the initial valuation.
This is an illustrative calculation, not an automatic purchase-price reduction. Actual valuations depend on market conditions, deal structure, financing, and negotiations. The example demonstrates why buyers should examine the evidence behind reported earnings before relying on those figures. Identifying unsupported adjustments earlier gives them an opportunity to request documentation, reassess assumptions, and prioritize further investigation.
How TrueQoE Brings Earnings Analysis Earlier
TrueQoE was developed to help transaction participants examine seller-reported earnings against the financial evidence available to support them before moving into more expensive stages of due diligence.
Through its First Pass analysis, users upload financial documents for an assessment that identifies discrepancies, reconciles figures with supporting records, and evaluates claimed earnings adjustments. The platform offers Buyer, Seller, and Advisor views to reflect the different responsibilities and priorities of acquisition participants.
TrueQoE classifies claimed add-backs in three ways:
- Documented: Available records provide supporting evidence for the adjustment.
- Needs Support: Additional documentation or explanation is required.
- Undocumented: Available evidence does not substantiate the adjustment.
The platform also distinguishes supported conclusions from unresolved questions and prioritizes recommended diligence steps according to materiality. This helps users understand which findings matter, what the available evidence establishes, and what should be investigated next.
Rather than simply calculating adjusted EBITDA, TrueQoE helps transaction participants distinguish documented facts from unresolved claims, identify the issues most likely to affect a deal, and determine where additional diligence is needed before making a consequential acquisition decision. Its self-service First Pass analysis, available for $499, provides an accessible starting point for preliminary financial review without requiring a sales call or an initial adviser consultation.
Why the Platform Emphasizes Evidence Over AI Confidence
TrueQoE’s development was shaped by Hirsch’s practical experience evaluating and operating businesses. Over more than 25 years, he has worked as an operator, buyer, seller, and adviser, evaluated more than 150 acquisition opportunities, participated in acquisition strategies, and been involved in operating and growing companies.
His experience evaluating businesses from a buyer’s perspective gave him firsthand exposure to the financial questions that can influence acquisition decisions. While working with an independent sponsor assessing HVAC businesses, he encountered limitations in general-purpose artificial intelligence tools. Some produced inaccurate financial figures, while using public AI systems raised concerns about the confidentiality of seller information.
These experiences highlighted the need for a more structured approach to examining financial documents, tracing calculations to supporting evidence, and identifying uncertainty before buyers commit substantial time and resources. That perspective informed TrueQoE’s development, with an emphasis on documentary support, transparent findings, and clear distinctions between established evidence and unresolved questions.
For Hirsch, the central question is not simply what earnings figure a seller presents, but how much of that figure can actually be supported by the underlying financial records.
TrueQoE also emphasizes that artificial intelligence should not override human judgment or replace documentary evidence. Its governing principles are designed to prevent unsupported assumptions from being presented as facts.
The platform includes Ask TrueQoE, an AI assistant focused on acquisition finance questions, and TrueQoE Insights, an educational resource covering financial analysis and business acquisition challenges.
A More Useful Starting Point for Buyers, Sellers, and Advisers
Although buyers are a primary audience, earlier financial analysis can benefit other participants in the acquisition process.
Sellers can use preliminary analysis to identify documentation gaps before bringing a business to market. Addressing questionable adjustments in advance may help create a clearer financial presentation and reduce avoidable questions during negotiations.
Brokers and M&A advisers can use structured financial analysis to identify potential concerns earlier. Lenders may also benefit from a clearer understanding of the earnings figures being discussed during preliminary financing conversations.
For first time buyers, search funds, and experienced business operators, the ability to examine financial claims earlier can help make acquisition decisions more informed.
However, TrueQoE is not a substitute for a formal quality of earnings engagement, audit, attestation, or lender mandated accounting diligence. Its First Pass product is intended for preliminary analysis before those more extensive professional processes begin. Users seeking additional professional involvement can choose a CPA assisted analysis performed by licensed members of the platform’s team.
Changing When Buyers Ask the Most Important Financial Question
The business acquisition process involves many decisions, but few are as important as determining whether the earnings presented by a seller are supported by reliable financial evidence.
As Mark Hirsch emphasizes, “Adjusted EBITDA is a claim until the evidence supports it.”
That principle reinforces why buyers should examine the documentation behind reported earnings rather than rely exclusively on the figures presented in a seller’s financial materials. Waiting until formal due diligence to test those assumptions can expose buyers to unnecessary costs, delays, and valuation uncertainty. A preliminary assessment can help identify discrepancies, distinguish supported adjustments from unresolved issues, and prioritize further investigation before an LOI.
TrueQoE’s First Pass analysis supports this earlier decision-making process, giving buyers and other transaction participants a more informed starting point for evaluating an acquisition.
Buyers, sellers, brokers, and advisers interested in understanding how TrueQoE approaches preliminary financial analysis can visit TrueQoE’s official website to learn more about First Pass and its role in the business acquisition process.
Disclaimer: This content is for general informational purposes only and should not be considered as financial advice. The content is not intended to be a substitute for professional financial advice, investment advice, or any other type of advice. You should seek the advice of a qualified financial advisor or other professional before making any financial decisions.