For established businesses with consistent revenue and a strong financial history, access to structured financing can support planned operational improvements. Whether a company needs additional equipment, wants to expand its facilities, or plans to refinance existing debt, selecting an appropriate financing structure requires careful consideration.
Fundivi provides business financing solutions through direct funding and a network of lending partners. Among its available products, Fundivi term loans are designed for qualified businesses seeking a defined loan amount with scheduled monthly repayments.
Understanding how these loans work can help business owners assess their financing needs and determine whether their financial position supports additional debt.
Understanding Business Term Loans
A business term loan provides a lump sum of capital that borrowers repay over an agreed period. Unlike financing arrangements that adjust repayments according to revenue, traditional term loans generally follow a predetermined payment schedule.
Fundivi term loans offer this structure to businesses seeking financing for identifiable expenses. According to the company’s website, available loan amounts range from $25,000 to $5 million, with repayment periods typically extending from one to three years.
Predictable repayments allow business owners to include debt obligations in their monthly budgets and cash flow projections.
For example, a company purchasing new equipment can evaluate its expected operating expenses alongside its scheduled loan payments. This helps management assess whether the business can maintain sufficient liquidity after borrowing.
However, fixed payments remain due even when revenue declines. Businesses should therefore consider seasonal changes, unexpected expenses, and their existing financial commitments.
Qualification Requirements for Established Businesses
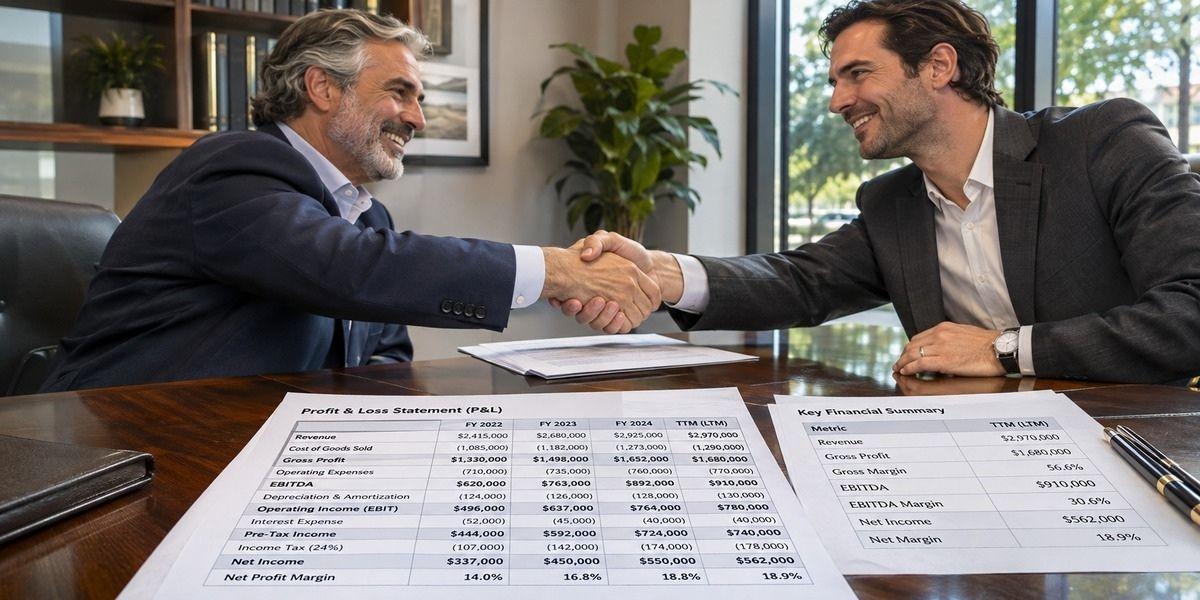
Fundivi term loans are intended primarily for established companies with consistent revenue and financial records that demonstrate repayment capacity.
The company’s term loan information identifies at least two years of operating history as an important qualification characteristic. Credit quality, revenue stability, and the intended use of funds also influence financing decisions.
Evaluating Business Financial Strength
Lenders generally assess several financial indicators when reviewing an application:
- Operating history: An established business history helps demonstrate operational stability.
- Cash flow: Consistent cash generation indicates whether existing operations can support additional payments.
- Credit profile: Personal and business credit histories provide information about previous borrowing behavior.
- Existing obligations: Current debt payments affect the amount of additional financing a company may reasonably support.
- Purpose of financing: A clearly defined use of funds helps lenders evaluate the requested amount.
The U.S. Small Business Administration (SBA) similarly emphasizes financial projections, credit history, and repayment ability when discussing business financing eligibility.
Meeting preliminary criteria does not guarantee approval. Final decisions depend on underwriting requirements and the borrower’s complete financial profile.
Business Applications for Term Loan Financing
Established companies may consider Fundivi term loans when financing needs involve clearly defined projects or purchases.
Businesses sometimes require machinery, technology, or specialized equipment to maintain operations or improve production capacity.
A term loan may allow the company to finance these purchases while spreading repayments across an established schedule. The financial benefit depends on acquisition costs, operating requirements, and the company’s ability to manage the resulting debt.
Companies planning additional locations or facility renovations may also evaluate Fundivi term loans as part of their financing strategy.
Before proceeding, management should estimate construction expenses, operational adjustments, and potential delays. Expected revenue should be assessed conservatively rather than treated as guaranteed.
Another potential application involves replacing existing business financing with a different repayment arrangement.
Refinancing may change monthly payment obligations, loan duration, and total borrowing costs. A lower monthly payment does not necessarily mean lower overall financing expenses, particularly when the repayment period increases.
How Fundivi Reviews Financing Applications
Fundivi term loans are offered through a financing platform that combines underwriting technology with direct lending capabilities and relationships with third-party funding providers.
According to its website, the company’s lending team has more than seven years of experience supporting business financing transactions. Fundivi reports having assisted over 3,000 businesses with funding across its broader financing services.
These figures are company-reported and should not be interpreted as independent performance guarantees.
The process begins when an applicant provides information about the business, financing requirements, and financial performance.
Fundivi evaluates relevant underwriting information and determines whether a request may fit its direct lending criteria or a participating funding provider.
Its website advertises same-day decisions and funding for many approved applications. Actual processing times depend on document verification, underwriting findings, and individual transaction requirements.
The company’s product information also indicates that term loan applications may require approximately four to seven supporting documents, depending on the circumstances.
Comparing Financing Costs and Repayment Terms
Before accepting Fundivi term loans, qualified business owners should examine the complete financing agreement rather than focusing exclusively on available capital or monthly payments.
Important considerations include interest rates, applicable fees, repayment duration, collateral requirements, personal guarantees, and possible prepayment conditions.
Borrowers should also calculate the total amount expected to be repaid throughout the financing period.
Resources such as Business Loans IQ provide information about business financing structures and loan comparisons. Independent comparisons may help borrowers understand differences between available financing arrangements.
The SBA also encourages businesses to prepare financial projections and review their ability to meet repayment obligations before pursuing financing.
The Importance of Responsible Borrowing
Fundivi term loans may provide a structured financing option for companies with established operations and documented repayment capacity. Nevertheless, financial strength alone does not establish whether additional borrowing is appropriate.
Business owners should evaluate expected expenses, available cash reserves, existing liabilities, and potential changes in revenue before entering a loan agreement.
A financing decision should reflect the company’s operational requirements and realistic financial projections rather than assumptions about future growth.
Disclaimer: This content is provided for general informational purposes only and does not constitute financial or legal advice, a financing offer, or a guarantee of loan approval. Business owners should independently review financing agreements and consult qualified professionals when appropriate.