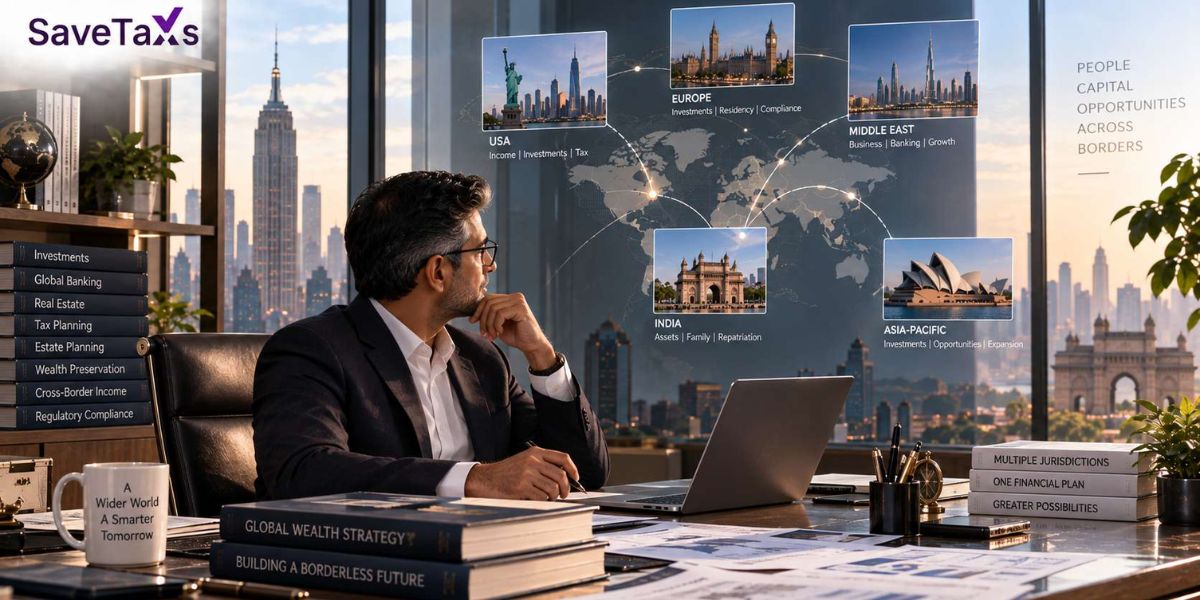
For globally mobile Indian executives, wealth is increasingly distributed across countries, currencies, investment structures and ownership interests. The strategic challenge is no longer managing each asset separately, but understanding how the pieces interact before major financial decisions are made.
For much of the corporate world, the balance sheet is a familiar concept that brings assets, liabilities, cash and investments together into a single financial picture.
For a growing group of executives, however, the personal balance sheet is becoming geographically distributed.
An executive may earn compensation in one country, hold equity in an overseas employer, retain property in India, maintain investments in another market and accumulate retirement assets under yet another jurisdiction’s rules.
None of those arrangements is necessarily unusual.
The difficulty begins when decisions involving one part of that structure affect another.
A change in employment can affect equity compensation. A relocation can change the tax framework applicable to an individual’s income and assets. The sale of an investment can raise questions about capital gains and reporting. A transfer of funds can introduce banking, foreign-exchange, tax or documentation considerations.
This is why cross-border financial planning is increasingly less about understanding individual assets and more about understanding the architecture connecting them.
For CEOs, founders and internationally mobile professionals, that distinction matters.
From a Portfolio of Assets to a Financial Architecture
The term “international wealth” can make a complex financial position sound simpler than it is.
An overseas investment is not just an investment. Its relevance can depend on where the investor is resident, where the asset is located, how returns are generated, how gains are treated and whether additional reporting requirements apply.
The same principle can apply to executive compensation.
An equity award may look like part of a compensation package, but its financial consequences can depend on factors such as vesting, exercise, sale and the individual’s circumstances at those points.
The executive therefore needs more than an inventory of assets.
They need a map.
That map should connect five questions:
Where is the individual earning?
Where are they resident?
What do they own?
What transactions are likely to occur?
Where will liquidity ultimately be required?
That is the beginning of a financial architecture.
It is also where cross-border financial planning becomes materially different from conventional annual tax preparation.
The Compensation Problem Is Becoming More Complex
Executive compensation increasingly extends beyond a monthly salary.
For senior employees and founders, remuneration may include salary, bonuses, stock options, restricted stock units, carried interests or ownership in private businesses.
When those interests cross jurisdictions, timing becomes important.
An executive who moves countries during the life of an equity award may need to understand the interaction between the compensation arrangement, the jurisdictions involved and the timing of relevant events.
This does not mean that every equity award creates a cross-border tax problem.
It means that executives should avoid treating compensation, investments and residency as completely separate subjects when they may interact.
The same principle applies to founders.
A founder might operate an Indian business while living overseas, hold shares in another jurisdiction and maintain personal investments in India. A business decision can therefore have implications for the individual’s broader financial position, while a personal relocation can potentially affect the context in which business interests are evaluated.
The strategic issue is coordination.
Indian Assets Do Not Stop Being Relevant After an Executive Moves Abroad
International mobility does not necessarily sever an individual’s financial relationship with India.
Property, investments, bank accounts, business interests and family wealth can remain connected to India long after an executive has established a career overseas.
That creates a financial planning challenge that is broader than taxation.
For example, an executive might need to consider whether an asset is intended for long-term wealth accumulation, family use, future liquidity or eventual transfer.
The tax treatment can then become one component of a larger decision.
The regulatory framework matters too.
India’s Income Tax Department confirms that residential status for tax years beginning on or after 1 April 2026 is determined under the Income Tax Act, 2025. The department also states that the basic individual residency tests remain substantially unchanged from the previous framework.
That distinction is important for internationally mobile individuals because tax residency is not simply a label attached to a person. It can influence the framework within which income and financial interests are evaluated.
For an executive, the practical lesson is straightforward: location, ownership and timing should be considered together.
The International Investment Question Is Bigger Than Returns
Executives often evaluate investments primarily through expected returns, risk and diversification.
For someone with assets across jurisdictions, the decision carries another layer of cross-border financial consequences.
An investment may need to be considered through several lenses:
● tax treatment
● reporting requirements
● currency exposure
● liquidity
● ownership structure
● future residency
● capital gains
● the eventual movement of funds.
The United States provides a useful illustration of this complexity.
The IRS states that US citizens and resident aliens are generally subject to US tax on worldwide income, while certain taxpayers with foreign financial accounts may also have additional reporting obligations. FBAR requirements, for example, can apply where the aggregate value of qualifying foreign financial accounts exceeds $10,000 at any point during the calendar year.
The point is not that every Indian executive with US connections faces the same obligations.
The point is that international investment decisions cannot always be evaluated in isolation from residency and reporting status.
The same principle can apply in other jurisdictions, although the rules differ.
Liquidity Is the Overlooked Part of International Wealth
There is another issue that receives less attention than tax: liquidity.
An individual can have substantial wealth and still find that much of it is difficult to access in the jurisdiction where it is needed.
Consider an executive with:
● property in India
● securities in the United States
● retirement assets overseas
● equity in a private company
● cash held across multiple banking relationships.
On paper, this may represent a diversified financial position.
In practice, it may require careful planning when the executive needs to fund a business, relocate, purchase an asset, support family members or transfer wealth between countries.
This is why repatriation planning should not be treated merely as a transaction that occurs when money needs to move.
It can be part of a broader liquidity strategy.
The Reserve Bank of India’s Liberalised Remittance Scheme also illustrates the scale of cross-border individual financial flows. RBI data show substantial outward remittance activity by resident individuals, reinforcing the importance of understanding the regulatory environment surrounding international movement of funds.
For individual planning, however, the relevant question is not the size of the aggregate market. It is whether a particular transaction fits the rules applicable to that individual.
The Real Problem Is Fragmented Advice
This is where the financial architecture becomes particularly important.
A globally mobile executive may have a tax adviser, investment adviser, banker, lawyer, accountant and financial planner.
Each professional may be highly competent.
Yet the executive can still have a coordination problem.
The investment adviser may be focused on portfolio performance.
The tax adviser may be focused on tax treatment.
The banker may be focused on the mechanics of moving funds.
The lawyer may be focused on legal structure.
The executive, meanwhile, has to make one decision.
This creates what could be called the coordination gap.
The issue is not necessarily a shortage of professional expertise. It is the absence of a single, coherent view of how the decisions interact.
For internationally mobile professionals, that gap can be more consequential than any individual tax rule.
A Better Framework for Cross-Border Financial Planning
Executives can start by organizing their financial affairs around decisions rather than products.
1. Map Income
Identify salary, bonuses, equity compensation, business income, rental income, dividends, interest and other material sources of income.
2. Map Ownership
Document property, securities, retirement accounts, private-company interests, bank accounts and other significant assets by jurisdiction.
3. Map Future Events
Identify likely events such as an equity sale, business exit, relocation, property transaction, investment change or major transfer of funds.
4. Map Obligations
Determine which jurisdictions may have tax, reporting, regulatory or documentation requirements relevant to those assets and events.
5. Map Liquidity
Ask where funds are likely to be required over the next one, three and five years, and whether the current structure can support those needs efficiently.
6. Review the Architecture Periodically
International financial structures change as careers, businesses, investments and residences change.
A financial architecture that made sense several years ago may not be appropriate after a major change in circumstances.
This framework is not a substitute for professional tax, legal or investment advice.
Its value is that it helps an executive ask the right questions before those decisions become difficult to reverse.
Where Technology Fits and Where It Does Not
Technology can make this process considerably easier.
Digital systems can help organize documents, consolidate financial information, identify missing data and structure complex workflows. They can also make it easier for advisers and clients to maintain a current picture of an individual’s financial affairs.
But technology does not eliminate the need for professional judgment.
Tax residency questions, international transactions, equity compensation, foreign investments and cross-border business structures can involve facts that cannot be resolved through a generic calculator or automated workflow.
Savetaxs’s experience with NRIs and globally mobile Indians reflects this broader movement toward technology-assisted tax and compliance workflows. The firm’s published materials describe its work across Indian and NRI taxation, capital gains, DTAA, repatriation and compliance.
In a 2025 company announcement carried by The Tribune, Savetaxs co-founder Shubham Jain said, “Our clients told us they struggled with basic questions like whether they count as Indian residents for tax purposes.”
The observation points to a larger issue. Before sophisticated financial planning can work, the underlying facts need to be understood and organized correctly.
What This Means for CEOs and Founders
The strategic implication is not that every executive needs another adviser.
It is that executives with internationally distributed wealth need visibility across the entire structure.
For a founder, that might mean understanding how personal ownership interacts with a business expansion or eventual exit.
For a senior employee, it might mean considering equity compensation alongside residency, investments and future mobility.
For an NRI investor, it might mean evaluating Indian assets alongside overseas investments rather than treating the two portfolios independently.
And for an executive considering a major relocation, the relevant financial planning may begin months before the move itself.
The common thread is timing.
The earlier the relationship between assets, jurisdictions and future decisions is understood, the more information an executive has when choices are still open.
The New Executive Financial Discipline
International wealth does not necessarily require an entirely new financial philosophy.
It requires a more integrated one.
The globally mobile executive’s financial life can no longer be understood purely through individual accounts, investments or tax returns.
It is a connected system.
Income influences investment capacity. Residency can affect the treatment of income and assets. Ownership structures influence future transactions. Liquidity determines how easily wealth can be deployed. Compliance obligations follow the underlying facts.
That is why cross-border financial planning is increasingly becoming a strategic discipline rather than simply an annual administrative exercise.
The most important question for an internationally mobile executive may therefore not be this one.
“What tax applies to this asset?”
It may instead be this one.
“How does this asset fit into the financial architecture I am building across jurisdictions?”
For CEOs, founders and global Indian professionals, that shift in perspective can create something more valuable than a perfectly organized tax file: the ability to make major financial decisions with a clearer view of their consequences.
Disclaimer: This article is for informational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any securities. Consult a qualified financial advisor for advice specific to your situation.